

Are you still worried about Admission Test Financial-Accounting-Reporting? I advise you to google "Prep4cram". We provide you Financial-Accounting-Reporting free demo download for your reference. Financial-Accounting-Reporting Prep & test bundle is very useful and similar with the real exams. If you are willing to pass exam at first shot you had better purchase exam cram, we will send you the exam cram PDF file. It is very available for reading at all electronics and printing out. The most important is that we guarantee: "No Pass, No Pay". We already help more than 3000 candidates pass this exam. We are proud to say that about passing Financial-Accounting-Reporting we are the best.
The Strength & Power of Our Company
We have a lot of experienced education staff from Admission Test who are ngaged in IT certification examination more than 8 years. They are familiar with past Financial-Accounting-Reporting real exam questions and they know update information about the Financial-Accounting-Reporting exam at first time. Our Financial-Accounting-Reporting Prep & test bundle or exam cram pdf are shown on the website with the latest version. Our IT staff will check the update every day.

Up-to-date Version, Latest, Valid
We promise Financial-Accounting-Reporting exam cram all we sold is the latest and valid version. If you have doubt about it, you can contact with us. Also you can compare our version with the other. Normally if it is not the latest version we won't say 100% pass rate, we will say 70%-80% pass rate and advise you waiting the updated version. We hereby specially certify that the Financial-Accounting-Reporting exam cram we say 100% pass is the latest and valid version. Do not hesitate about it, just buy it
Our Golden Service
Firstly we are 7*24 on-line services, once you contact with us we will reply you in two hours;
Secondly we have one-year warranty service since you buy. We will send you the updated Financial-Accounting-Reporting exam version within one year if you accept. No matter you have any question you can email us to solve it.
Thirdly we will keep your information safe. Even our service customers can't see your complete information. We have a strict information protection system.
Fourthly we guarantee Financial-Accounting-Reporting exam 100% pass rate if you study our Financial-Accounting-Reporting prep material hard. But if you fail the exam please provide the unqualified certification scanned and email to us. Once we confirm it we will full refund to you.
Fifthly if you buy Financial-Accounting-Reporting exam cram for your company and want to get the latest version in next several years we are free to serve you in one year and you can give 50% discount Financial-Accounting-Reporting Prep & test bundle in next year. Also after you buy you will have priority to get our holiday discount or sale coupon. If you pass Financial-Accounting-Reporting exam and want to buy other subject we can give you discount too.
All in all we have confidence about Financial-Accounting-Reporting exam that we are the best. If you want to pass it successfully please choose our Financial-Accounting-Reporting exam cram pdf. You will be happy about your choice. It's certainly worth it.
Admission Test Financial-Accounting-Reporting Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Select Transactions | 25-35% | - Leases - Derivatives and Hedge Accounting - Fair Value Measurements - Business Combinations and Consolidations - Subsequent Events and Fair Value Disclosures |
| Topic 2: Select Financial Statement Accounts | 30-40% | - Expenses and Other Items - Revenue Recognition - Equity - Assets - Liabilities |
| Topic 3: Financial Reporting | 30-40% | - General Purpose Financial Statements - Special Purpose Frameworks - State and Local Government Reporting - Financial Reporting for Nonprofits - Conceptual Framework and Standard-Setting |
Admission Test Certified Public Accountant (Financial Accounting & Reporting) Sample Questions:
The following question is based on the following:
Vane Co.'s trial balance of income statement accounts for the year ended December 31, 2002, included the following: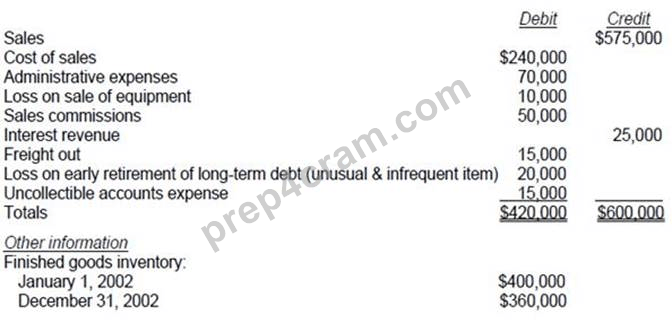
Vane's income tax rate is 30%.
In Vane's 2002 multiple-step income statement, what amount should Vane report as income from continuing operations?
- A. $140,000
- B. $147,000
- C. $126,000
- D. $129,500
How should the effect of a change in accounting principle that is inseparable from the effect of a change in accounting estimate be reported?
- A. By footnote disclosure only.
- B. As a correction of an error.
- C. As a component of income from continuing operations.
- D. By restating the financial statements of all prior periods presented.
While preparing its 1991 financial statements, Dek Corp. discovered computational errors in its 1990 and 1989 depreciation expense. These errors resulted in overstatement of each year's income by $25,000, net of income taxes. The following amounts were reported in the previously issued financial statements: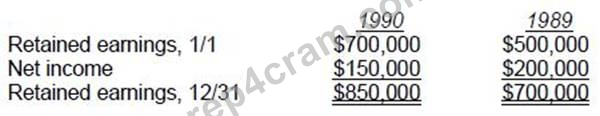
Dek's 1991 net income is correctly reported at $180,000. Which of the following amounts should be reported as prior period adjustments and net income in Dek's 1991 and 1990 comparative financial statements?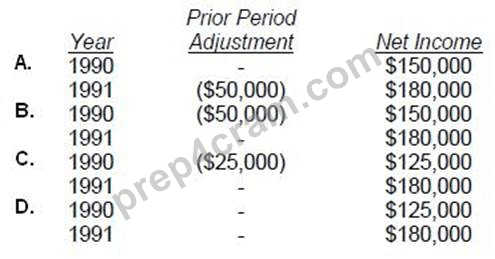
- A. Option A
- B. Option B
- C. Option D
- D. Option C
Tack, Inc. reported a retained earnings balance of $150,000 at December 31,1990. In June 1991, Tack discovered that merchandise costing $40,000 had not been included in inventory in its 1990 financial statements. Tack has a 30% tax rate. What amount should Tack report as adjusted beginning retained earnings in its statement of retained earnings at December 31, 1991?
- A. $150,000
- B. $190,000
- C. $122,000
- D. $178,000
Grum Corp., a publicly-owned corporation, is subject to the requirements for segment reporting. In its income statement for the year ended December 31, 1991, Grum reported revenues of $50,000,000, operating expenses of $47,000,000, and net income of $3,000,000. Operating expenses include payroll costs of $ 15,000,000. Grum's combined identifiable assets of all industry segments at December 31, 1991, were $40,000,000.
Cott Co.'s four business segments have revenues and identifiable assets expressed as percentages of Cott's total revenues and total assets as follows: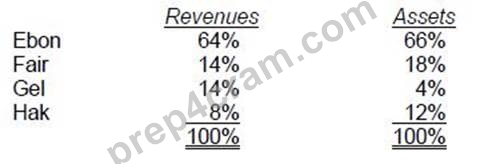
Which of these business segments are deemed to be reportable segments?
- A. Ebon and Fair only.
- B. Ebon only.
- C. Ebon, Fair, Gel, and Hak.
- D. Ebon, Fair, and Gel only.


